
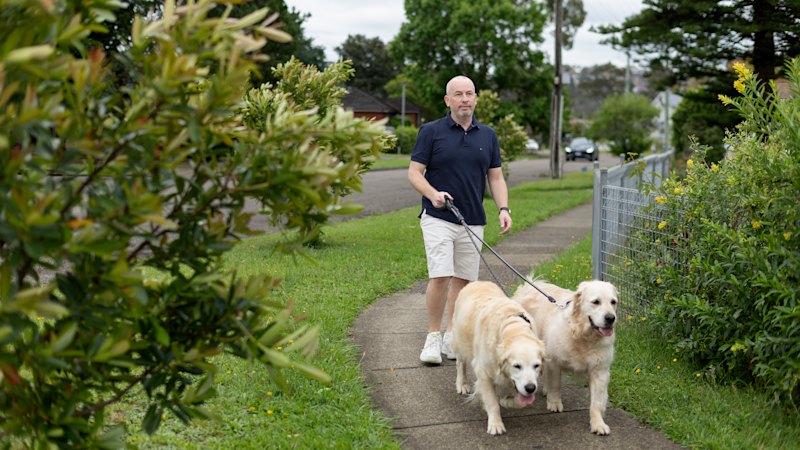
November 7, 2026 — 5:00amBen Sandland was looking for the Great Australian Dream – a backyard, a barbecue and space for a couple of dogs. He found that in the form of a solid brick home in Constitution Hill, west of Parramatta, but a hoped-for renovation is yet to happen.“With the pandemic, various wars, interest rate rises, inflation rises, I haven’t been able to do as much to the house as I’d like to,” he said of the four-bedroom property he bought in 2017.Sandland, 49, had expected to be a much different position nine years after swapping an apartment for a house. But he said the high cost of living doesn’t allow him extras like renovation, overseas travel or hobbies, which makes him feel there is less to look forward to.Home owner Ben Sandland walks his golden retrievers, Winston and Bailey, in Constitution Hill on Wednesday. The Reserve Bank lifted the official cash rate by 0.25 percentage points to 4.85 per cent on Tuesday, marking the fifth interest rate hike of 2026. Sitthixay DitthavongHouseholds have been fending off cost-of-living pressures and higher interest rates, and NSW is sensitive to rate increases as more of borrowers’ income is spent on servicing a loan than in other states.The Reserve Bank on Tuesday raised rates for the fifth time this year to 4.85 per cent – the highest since 2008, adding about $100 in monthly repayments to a $600,000 mortgage.IT worker Sandland has no problems meeting his mortgage repayments, but the hikes have curbed his lifestyle and his hopes for the future. He has pressed pause on adding more to his investments, instead putting those funds into his offset, and has no plans for international travel, despite earning a good income.“There’s not really much discretionary income left, so it’s all going to trying to pay off the mortgage faster and trying to avoid that higher rate … I think overall optimism is really low. So, it’s just like existing and going through the motions as opposed to anything to look forward to at the moment,” he said.“Also being in IT, I’m worried about AI effectively coming in and taking that job away in three years or five years … I feel almost like I have to be a prepper these days.”Mortgage stress mountsConstitution Hill, which overlooks the Parramatta skyline, has a small shopping strip with a destination patisserie. It is marked by a collection of cul-de-sacs and native gum-dotted streets, some named after orchard fruit in a nod to the suburb’s agricultural heritage. On 2021 Census data, 28.1 per cent of homes in Constitution Hill were owned outright, versus 31.5 per cent statewide, while 29.7 per cent were owned with a mortgage, slightly less than the state average.The Constitution Hill retail strip has an art shop, a pâtisserie and also houses the local library.Sitthixay DitthavongBut not everyone in the suburb has been able to meet their home loan commitments. Around one in 40 Constitution Hill borrowers – 2.42 per cent – in the suburb are behind on their mortgage repayments, the highest proportion in NSW, S&P Global Ratings data shows. Outer suburbs in Sydney feature heavily in S&P’s list of postcodes where borrowers slipped behind. At the end of June, five of the 10 Australian suburbs with the highest level of arrears were in NSW.These include the family-friendly suburb of Baulkham Hills, where 2.26 per cent of borrowers were late. This was followed by Berkshire Park (2 per cent) and Casula (1.96 per cent), in the west and the semi-rural postcode of Alison (1.78 per cent). Constitution Hill has the second-highest level of arrears in Australia.Over the past year, Sydney and Melbourne postcodes have dominated the list, said Erin Kitson, an analyst at S&P.“While postcode data is volatile due to small sample sizes, the trend suggests mortgage stress has been more pronounced in areas with higher debt-to-income ratios and more pronounced property price declines,” she said.Focusing on loan sizeMortgage pressure is in Bryan Hoger’s rearview mirror, but it remains front of mind with his children managing home loans during uncertain times.Home owner Bryan Hoger in Constitution Hill wonders how people with large mortgages are able to pay them.Sitthixay DitthavongHoger, 72, a retired mechanical designer, bought a small fibro home in Constitution Hill in the mid-1970s for $29,000. He and his wife are still living in what became the family home after a later renovation, now mortgage-free. Despite being self-funded retirees, Hoger said the couple were noticing “at the checkout” the cost of living had been increasing.The couple’s daughter, 32, bought a home in a regional town down south, while their son, 28, recently purchased a two-bedroom unit near Constitution Hill, with plans to move there in January. “It’s fortunate, in both cases, they’re pretty well in their positions … and both of them have got good partners which will end up helping. So, in that sense I don’t foresee any major financial problems for them,” he said, noting it would probably be harder for a solo borrower.Hoger said his children’s loans were relatively small.“Compared to these $800,000 to $900,000, million-dollar loans. I don’t know how they pay them back,” he said.Feeling the most pressureConstitution Hill’s arrears level was nearly three times the national average of 0.85 per cent.“The national number doesn’t tell you much here. Most borrowers are coping. The stress is concentrated in particular pockets, usually ones with a lot of recent buyers on big loans,” said chief executive of mortgage broker Finspo, Angus Gilfillan.“Many of them borrowed as much as they could, close to peak prices, when rates were lower. Five rises later, their home is worth less, and they haven’t had time to pay much down.”People were cutting back on essentials or working extra hours, said Gilfillan. Some were going interest-only, stretching their loan to 30 years, or asking for a sharper rate. But refinancing conversations can stall if borrowers can’t pass the test for a new loan.Manny Laris, 39, lives in Greystanes, about 15 minutes away from Constitution Hill, where he owns an exercise business, Bforty Pilates.Manny Laris, owner of Bforty Pilates in Constitution Hill, says his clients are looking for ways to save money amid higher rates and cost of living pressures.Sitthixay DitthavongHe had considered refinancing the mortgage, but said that was “difficult” in this climate.“You’re kind of stuck between a rock and a hard place, and all you can really do is just pick up extra hours, work more,” he said. “Especially if you’ve got a family, you’ve got to do everything you can to keep a roof over your head.”His business in Constitution Hill is one of three Pilates studios he owns in western Sydney. He has modified his business model to adapt to economic conditions and the needs of clients – who are also feeling rate pain. Some are downgrading memberships or looking for the most cost-effective option, he said.“I try to do whatever I can to make our services as affordable as possible … and create a situation that makes it feasible for people to continue, so people don’t have to give up something that actually helps improve their health, especially their mental health, the way things are.”Laris and his wife bought their home in 2020, but lived with relatives as they saved to do a knockdown-rebuild. The couple, who have three young children, moved into their new home last year, but higher rates have added pressure and taken family holidays off the agenda.“We’re just trying to make sure that we’re on top of our bills, being really careful with our spending, just buying the bare essentials that we need to get through until things start to hopefully improve.”Property alerts are now available in the SMH app. Turn them on to receive the latest market news and trends.Property listingsFrom our partners
What life’s like in Sydney’s most mortgage-stressed suburb
Full Article
Original Source
Read the full article at Smh →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.