
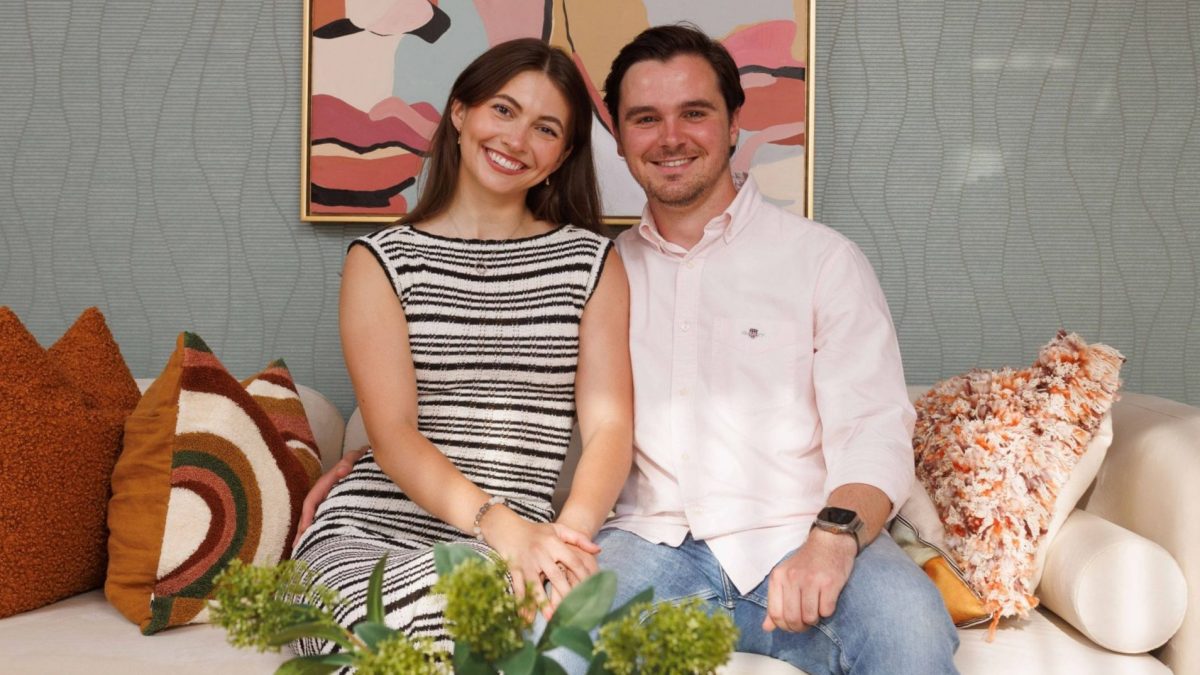
Benjamin Southgate and Chloe Roberts recently found out their landlord is selling their rental home in London and have decided to buy their own flat – but it hasn’t been built yet. Whilst Labour is understood to be mulling the return of Help to Buy to give first-time buyers more support, in the interim, some first-time buyers are using different routes to get on the property ladder. Benjamin, 27, a management consultant, and Chloe, 25, an accountant, are a couple who did just that, purchasing their first home off-plan. The pair started dating in 2018 and live in a rental property in Tooting Bec with one housemate. Shorts Benjamin said: “We moved to our current property in August 2024. It’s a converted garage at the rear of an old bakery. The two of us each pay £955 a month for rent and our housemate pays slightly less.” Earlier this year, the couple’s landlord told them he planned to sell the property, partly as he did not want to be affected by changes in the Renters’ Rights Act. So, in January, Benjamin and Chloe started looking for their own home. “We wanted to start building equity in a home. Our initial planned budget was about £250,000 to £300,000. Later on, we realised we could borrow more,” Benjamin said. None of the couple’s friends in London have purchased their own home yet. Chloe told The i Paper: “We’d both started saving for a deposit from the age of 18. We each saved £20,000 via stocks and shares ISAs and got a total of £20,000 from our parents, so our total deposit was £60,000.” The couple looked at various properties, including an older basement flat in Putney, a flat with a £6,000 annual service charge and one with possible cladding issues. But their heads were turned by a new-build site yet to be completed called The Lanes in Tooting, being built by Barratt Homes. It has not been built yet as the couple are buying an off-plan flat. Often these are based on an architect’s plans and sometimes a show home. They discounted older homes they would have needed to renovate. Benjamin said: “We’ve plumped for a one-bed ground floor flat in The Lanes development. The flat was listed for £450,000 and we got it for £427,500. Our service charge hasn’t been fixed yet.” The couple paid a £99 reservation fee and £5,000 as the first instalment of their deposit when they exchanged contracts. Two weeks before completion, they will pay the remainder of the balance of the £60,000 deposit. The couple secured a mortgage via a broker recommended to them by the developer. The interest rate on their mortgage will be 4.96 per cent and the deal is valid for 12 months. They will pay £1,742.68 a month for their monthly mortgage repayments. “We’ve been given a target completion for April to June 2027. There’s no fixed date but we are comfortable with that. It’s exciting and we can build up our savings further in the interim as we don’t have to pay the whole deposit now”, Benjamin said. Fortunately, their landlord is letting the couple live in their rented home until they can move into their own. Chloe added: “Had we moved in immediately, we would have had no cash left. Now we have some breathing space.” What risks to consider before buying a property off-plan Buying an off-plan home can be a good option for buyers who want a low-maintenance home and are not in a rush to move. But there are risks to consider. Richard Wisnia, head of new build development at Switalskis Solicitors, said: “Essentially, when buying off-plan, you don’t have certainty about when the new home will be ready to move into.” The developer expects buyers to exchange contracts within four to six weeks of a reservation agreement being completed. The potential for snagging also needs to be considered. Wisnia said: “New houses are built by people, by hand. This means there may well be imperfections in the finished product. The process of “snagging” – the check for minor defects – is enshrined in the New Homes Quality Code. “This allows you to send in a professional surveyor to inspect the property on your behalf during the period between the completion of the construction and legal completion and produce a report on any minor defects found.” If you are using mortgage finance, get clarification about how long the formal offer of mortgage will last for. This is usually six months initially from the date of the offer, but for new-builds these can be extendable. Laura Walker, director of residential property services at Lyons Bowe solicitors, said: “Buyers may exchange many months before completion and their mortgage offer could expire before the flat is ready. “If they have to reapply, interest rates, lending criteria or their own financial circumstances may have changed, and a lender could ultimately value the finished property at less than the agreed purchase price. “Buying off-plan can work extremely well, but buyers should go into it with their eyes open and obtain proper legal and mortgage advice before committing.”
We bought our first home for £427,000 – but it hasn’t been built yet
Full Article
Original Source
Read the full article at Inews →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.