
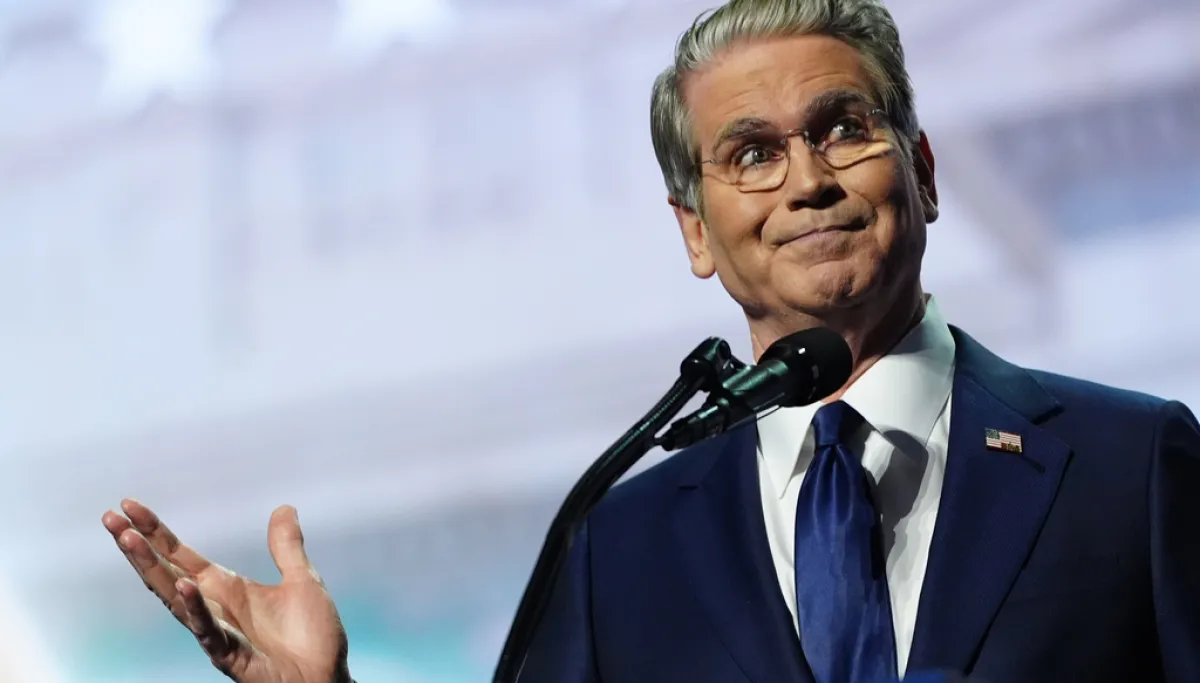
During political campaigns, candidates often make promises that sound plausible but prove fanciful in practice.Take hedge fund executive-turned-Treasury Secretary Scott Bessent. Bessent soon promoted his “3-3-3” plan: reduce the federal deficit to 3% of GDP, lift sustained real GDP growth to 3%, and deregulate energy markets to expand domestic crude oil production by 3 million barrels per day.As I predicted, reality has fallen well short of those targets. Today, the federal budget deficit sits at near 5.5% of GDP. Economic growth has hovered around a 2% annualized pace, while domestic oil output has climbed by only about 1 million barrels per day. With the November midterm elections fast approaching, Bessent has shifted to a familiar argument: that the United States can painlessly solve the fiscal problem through sustained faster economic growth. This fiscal problem is undoubtedly a serious one. Debt held by the public stands at roughly $31 trillion, matching 100% of GDP. To compound the challenge, federal borrowing costs have climbed sharply this year. Because the debt-to-GDP ratio is around 100%, each 1% increase in the average interest rate on Treasury debt adds roughly 1% of GDP directly to annual borrowing needs.Can stronger economic growth actually resolve this fiscal challenge?Some technology optimists argue that breakthroughs in artificial intelligence could accelerate sustained annual growth to 4–5%. Anthropic CEO Dario Amodei has even suggested that once AI is thoroughly integrated into the economy, mid-teens growth rates are conceivable. Yet such hypergrowth would almost certainly stem from widespread automation of human labor, a disruption voters and policymakers would hardly accept without substantial welfare protections, which would put pressure on public finances.The hard truth is that outgrowing the current fiscal gap without spending cuts or revenue increases is mathematically improbable.While targeted deregulation can lift productivity at the margin, historical precedent and debt arithmetic show why expansion alone cannot close a structural deficit exceeding 5% of GDP. Net interest payments already surpass $1 trillion annually, consuming more than 3% of economic output. With effective borrowing rates around 3%, matching that figure with 3% real GDP growth merely stabilizes debt accumulation. It does not bend the curve downward. Furthermore, the American economy has not averaged 3% growth over any sustained multiyear period since the late 1990s.Sustaining even 3% growth faces formidable structural headwinds: an aging workforce, slowing population growth, and restrictive immigration policies that limit inflows of high-skilled talent. Achieving it would require an unprecedented surge in productivity, particularly in lagging sectors such as healthcare, which accounts for nearly a fifth of output. President Donald Trump’s broad-based tariffs further dampen productivity momentum by raising the cost of critical capital goods and intermediate inputs.THE GOP’S TENT IS TOO BIG IF BO FRENCH FITS UNDER ITEven under optimistic growth assumptions, spending constraints persist. More than 60% of federal outlays fund mandatory programs, predominantly Social Security and Medicare. Demographic shifts automatically push these obligations higher regardless of top-line economic gains. Inflation indexing of such benefits compounds the problem. Faster growth is essential, but it does not solve the problem. Any credible path toward fiscal stabilization will ultimately require politically difficult choices: broadening the tax base, reforming entitlements, and curbing structural spending rather than relying on fanciful forecasts.James Rogan is a former U.S. diplomat who later worked in law and finance for over 30 years. He writes a subscription-based daily note on markets, economics, politics, and social issues. His email is [email protected].
Scott Bessent is wrong. The US can’t grow its way out of the deficit
Full Article
Original Source
Read the full article at Washingtonexaminer →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.