
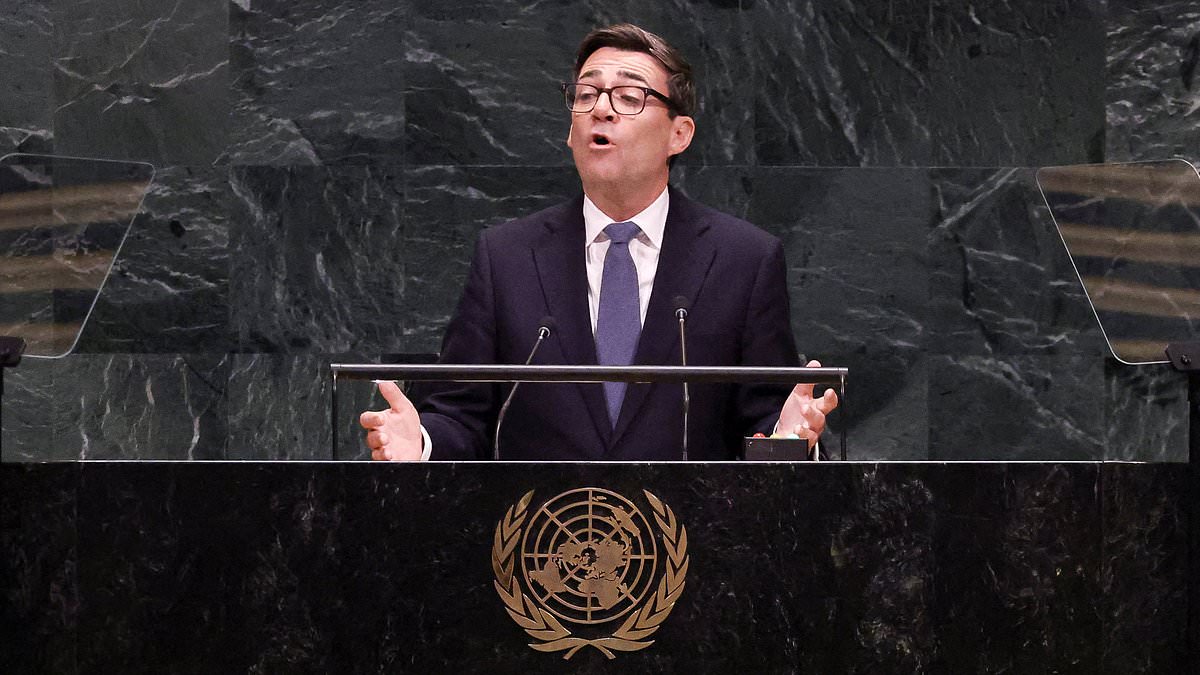
Labour has been hit with a pre-Budget triple-whammy as bleak figures suggested the UK economy is already close to flatlining.Closely-watched PMI data showed activity at the lowest levels in three months amid mounting inflationary pressures.Meanwhile, the influential OECD has downgraded forecasts for UK GDP next year, pointing to the impact of the Middle East crisis.And the IMF has issued a stark warning about debt levels in Britain and other major states, insisting Governments must take 'tough' decisions.Chancellor John Healey is facing an increasingly toxic backdrop to his first fiscal statement on October 28, with fears mounting that he will hike taxes to balance the books. He is also scrambling to fund expensive promises made by Andy Burnham, including on defence spending. Tories are urging Labour to curb benefits instead of upping the burden on families and business - who are already being battered by higher energy costs and the threat of interest rate rises.But any such move would meet fierce resistance from Labour MPs. Mr Burnham sounded defiance today despite the evidence that his options are being closed down. Andy Burnham sounded defiance today despite evidence that his Budget options are being closed down Closely-watched PMI data showed activity at the lowest levels in three months amid mounting inflationary pressures In an interview with the New Statesman, he suggested he will use Labour conference next week to 'dial up' his 'Manchesterism' push.Although the detail of that platform remains murky, the PM has vowed to roll back 'neoliberalism', unwind Thatcher reforms and increase public ownership. 'People might say you get into government and you dial down. I don't feel like that. I won't be dialling it down, put it that way,' he said. The closely watched S&P Global flash UK composite PMI - based on a survey of key business managers - recorded a reading of 51.7 for September.That was down from 52.5 in August. While any score above 50 indicates expansion, that is roughly equivalent to GDP growing by a bare 0.1 per cent in a quarter.Meanwhile, the rate of input price inflation rose for the second month in a row to reach its highest since June as soaring energy and fuel prices caused by the Iran war take their toll.Chris Williamson, chief business economist at S&P Global Market Intelligence, said: 'September is seeing a worrying combination of disappointingly sluggish economic growth and intensifying inflationary pressures, with subdued business confidence and high costs meanwhile continuing to discourage hiring.'Mr Williamson added: 'Growth, business confidence and employment are all being hamstrung by high energy prices, elevated business costs, geopolitical worries, higher market borrowing costs and uncertainty over Government policy at home in the run-up to the autumn Budget.'The report showed activity slowed across both the UK's services and manufacturing sectors.That casts doubt on the latest OECD growth outlook for the UK this year, which has been upgraded from 0.9 per cent to 1.1 per cent.That would still only be half the pace of US growth, at 2.2 per cent – again falling short of Labour's manifesto ambition to achieve the strongest growth in the G7 group of major advanced economies.And the OECD now thinks the UK will grow by just 1 per cent in 2027, down from a previous forecast of 1.1 per cent.If official forecasts produced alongside the Budget follow suit there will be significant implications for the public finances. Back in March, the Office for Budget Responsibility (OBR) had projected 1.6 per cent growth for 2027.In another gloomy message, IMF chief Kristalina Georgieva has said Governments are failing to take 'tough' decisions needed to stabilise their books.Speaking to the BBC on the sidelines of the UN General Assembly in New York, Ms Georgieva warned that Governments needed to show 'courage'.She said successive economic shocks had been 'pushing debt levels up like a staircase not to heaven' but there was 'no action to contain that service cost'.The IMF managing director said: 'There are these two things that must be done: bring debt levels down, put fiscal consolidation as a priority, and make sure that the central banks deliver on their mandate for price stability.'It is impossible to stress strongly enough how critical it is to get the courage to take the steps that are necessary. These are politically tough steps to take, but necessary steps to take.'Ms Georgieva said the UK's position was 'not very different' from other major states, despite nervous investors driving up interest rates on borrowing.She suggested there was 'fairly consistent action' on lowering debt, but warned Governments 'don't have the cash' to boost growth and must encourage the private sector to invest.In his interview, Mr Burnham did nod to concerns that investors are pricing in more risk to the UK's debt - after he caused alarm last year by hinting he wanted to ignore the bond markets.'I mean, the point about the bond markets, it holds – in that what I was saying was the country has left itself over-exposed.' IMF chief Kristalina Georgieva said Governments were failing to take 'tough' decisions needed to stabilise their books Mr Burnham argued that he was not calling for spending restraints to be abandoned, but rather making the case for 'a much more streamlined, productive state'.Economists warned the 'walls are closing in' on Mr Healey yesterday as figures showed Government borrowing surging.The public sector borrowed £18.3billion last month, up around a fifth on August 2025, as rising tax revenues failed to keep pace with Labour's spending.That was around £3billion more than expected, and £3.5billion more than the Treasury's Office for Budget Responsibility (OBR) watchdog predicted.Some £8.8billion went on interest payments for the debt mountain, which was hovering just below £3trillion.
Pre-Budget triple whammy as figures show UK economy already nearly flatlining with forecasts cut and IMF issuing debt warning... but Burnham insists he will 'dial up' Manchesterism
Full Article
Original Source
Read the full article at Dailymail →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.