
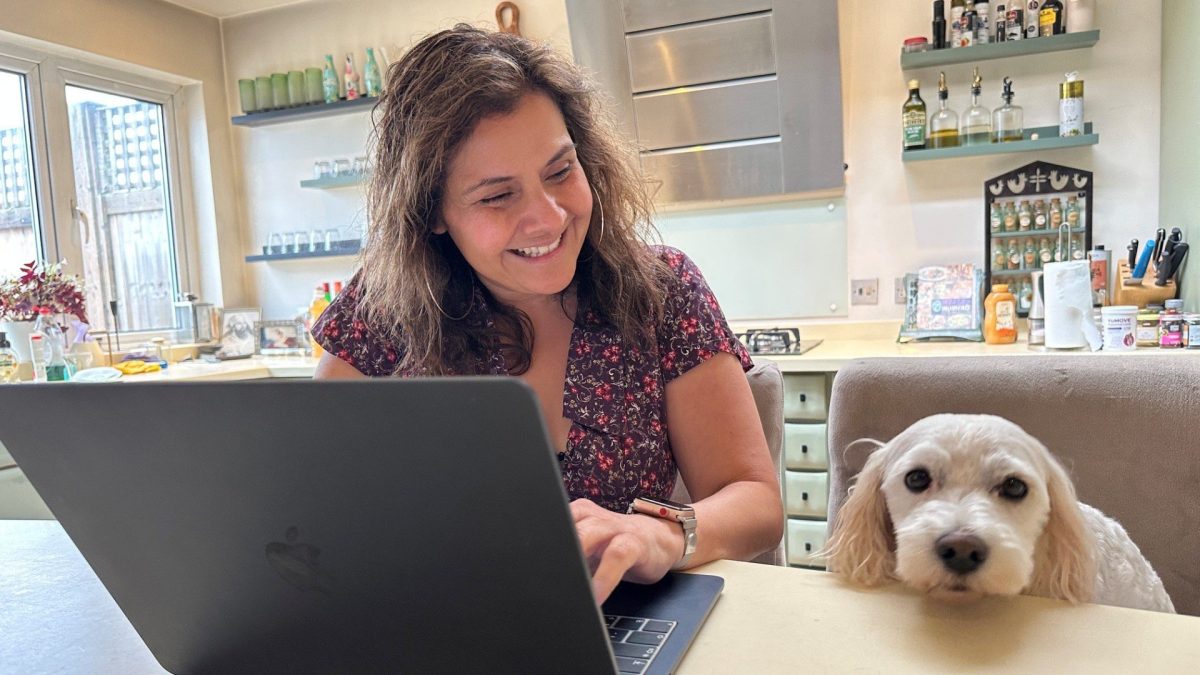
In our How I Manage My Money series we aim to find out how people are spending, saving and investing to meet their costs and achieve their goals. This week, in our celebrity edition, the actor and writer Nina Wadia talks about working in a restaurant at age nine and how Goodness Gracious Me helped her afford her first home. When did you first become aware of money? Probably when I was nine and started helping mum and dad at their restaurant in Hong Kong. That’s Indian families for you, the running joke of child labour! I’d go from school and help lay the tables. I couldn’t touch anything around the bar, but I’d greet customers, and by 11 I was waitressing. I would get a bit of pocket money, HK$2.50 (24p in 1979) a shift, and I thought, this is good – I can go to the tuck shop at school and buy noodles. It was very exciting. I learned that if you work hard at something, you get something in return and can buy what you want. Shorts Did your parents give you any guidance on what to do with your money? Yes, very much so, because we came from, let’s say, a modest background. There were five of us in a one-bedroom flat in India. There was never any pocket money when I was little because there was none to give. When I earned pocket money at the restaurant, they’d say, “You must spend some of it, save a little of it, and keep a tiny bit behind for charity.” Did you ever consider going into the restaurant trade? I’ve always had a quiet dream of owning a restaurant, but then I remember how hard it is, and I think it would be the stupidest thing I could possibly do. Anything in hospitality is difficult, but I have such respect for people who do that job. Did you go into acting from school? I went to drama school, and worked several other jobs before I got my first acting job. I washed cars, was a valet, a waitress, and I worked in accounts for an advertising firm. At £11 an hour or £385 a week, I earned more money doing that than I did in the first four years of my acting career. How did you get by in the early days? I remember paying £60 a week rent in a council flat, when I was earning around £240 a week, and travel was so expensive. I would jump the turnstiles at the Tube when I didn’t have enough money to buy food for the week. I had to become very good at budgeting. Nina’s daughter, Tia, pictured, wants to be an artist. Nina says she’s taught her children how difficult it can be to break into creative industries Were you worried about your finances back then? I was happy just surviving because I was finally doing what I wanted, and that keeps you going. Money has never really meant anything to me apart from independence. I’m not the type of person who must have Nike shoes. I have respect for money, and I hope I’ve passed that on to my children. Both of your children are pursuing careers in the arts, does this worry you? I can’t say to Tia [my daughter] who is a budding artist, or Aiden [my son] who wants to be a drummer like his dad, that it’s going to be really difficult. They know that already. They’ve seen me struggle to get work, seen me depressed. Provided they have jobs to support themselves while they pursue their careers, which they do, and they are happy, that’s all that matters. When did you feel you were financially secure? I’ve never felt financially secure. As an actor, you never do. I call them my Waitrose and Iceland years because if it’s been a good year it is a Waitrose Christmas, if bad, a basic Iceland Christmas. Either way, you have to be careful with money, as you can never guarantee what you’ll earn in the future. Do you own property? When I was doing EastEnders, I’d always get people asking if I live near Buckingham Palace, and I’d wonder what they thought I earned! I don’t live in central London. I have a five-bedroom bungalow in Surrey, which I share with my husband Raiomond Mirza, and Tia. Are you a spender or a saver? I used to be a spender. I love to travel and would spend all my spare money on family holidays, to Thailand or all around Europe in the car. I became a saver after Covid, because if it had lasted any longer I’d have had to borrow some money, and I don’t like doing that. Also, I hate having a mortgage, and want to pay it off. What’s your top money tip to anyone wanting to break into acting or comedy now? A study found around 1 per cent of actors are employed at any given point. So, my advice to anyone going into the acting profession is to have a backup job that gives you a steady income. It should be a temporary one you can drop if you get an acting job. Be prepared not to be successful as an actor – otherwise, you’ll drive yourself crazy waiting by the phone. Did you ever come close to jacking it in? I was at the point of giving up seven years into my career. I was sitting in the green room at Theatre Royal, Stratford East, bemoaning yet another spear-carrying role, yet another “best friend of the girl next door”. The artistic director, Philip Hedley, heard this and said, “Well, get off your fat arse and write something then! You’re a writer, create work, don’t expect it to just turn up.” This led to the stage show Do You Eat With Your Fingers, which became Goodness Gracious Me. Was Goodness Gracious Me a good earner? Not at all. It paid more than theatre, but was still terrible money for a TV actor. People say, but you did a series. A series in the UK at that time was six episodes, so really not that much work. What it did allow me to do was put away a bit more towards a mortgage, but it still took years to save around £10,000 for the deposit on a £70,000 two-bed flat in Sutton. What are you up to now? I’m launching my YouTube podcast called WadiaWannaKnow?! before Christmas. It’s green room chat, talking to all these very famous people about all the funny, hard times they’ve had to become successful.
Nina Wadia: I was on the verge of quitting, then I wrote Goodness Gracious Me
Full Article
Original Source
Read the full article at Inews →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.