
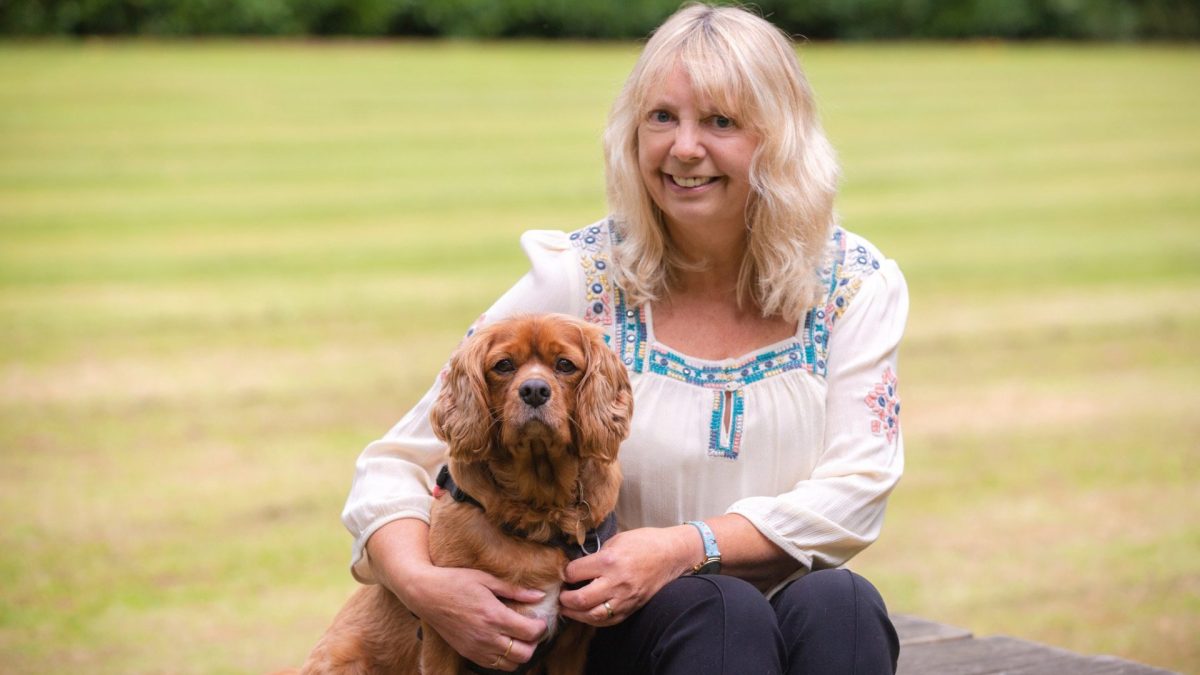
First-time buyers are borrowing for mortgages lasting an average of more than three decades because of affordability pressures. This could leave them borrowing until retirement – unless they take action. It’s why many people prioritise overpaying their mortgage to reduce what they owe and even pay off their mortgage decades early. Shorts Though the rules vary from lender to lender, most banks will allow you to overpay 10 per cent of your mortgage balance each year without penalty – though always check before you do. The i Paper spoke to three different people about their mortgage overpayment stories and the different methods they used to shave years off the length of their mortgage. ‘I prioritised my mortgage over my pension’ Sandra Emmons remembers her dad always telling her: “Your biggest debt is your mortgage” and “Always aim to pay off your biggest debt first”. So knowing she had a mortgage which was not due to be paid off until she was in her mid-seventies gave her the determination to overpay as much as she could, which culminated in her becoming mortgage-free 20 years earlier than anticipated at the age of 56. Sandra, now 62, who lives near Reading, Berkshire, lives mortgage-free in her two-bedroom cottage with her partner and dogs. The property is on what used to be a country estate and was one of the stables, which was converted into a cottage in the 70s. “I used to live in a flat on the same estate which was a repossession and I paid £45,000 for it,” she explained. “Then around 14 years ago, I sold it for £220,000 which allowed me to buy the cottage I am in now for £290,000 with a £90,000 mortgage.” Sandra, who worked as a service director for a maintenance company for 23 years, took out a 25-year term on her mortgage as that was the only way she could afford it. But she made overpaying her mortgage a priority. “I was really careful about what I spent and whenever I got my pay, the overpayment for my mortgage went out first and I then eked out whatever I had left. “I paid a basic amount into my pension and prioritised overpaying my mortgage instead. I could overpay around £10,000 a year, so I tried to pay off as much of that as I could.” After paying off her mortgage in 2020, Sandra had the confidence to quit her job and work full-time with her dog-training business Happipup. “I had been studying to become a dog trainer for 16 years and had been working on it during weekends and evenings around my full-time job, but paying off the mortgage meant I could finally do it full-time.” Sandra admits she does sometimes have a “wobble” as her private pension pot is less than £100,000. However, she says that she feels that this, together with her state pension at 67, will be enough for her. “I have no regrets about sacrificing my pension for my mortgage as not having to worry about paying a mortgage is a huge positive.” ‘I paid my mortgage off at 43 by paying the same when rates plummeted’ Rachel Lancaster and her husband met when they were teenagers and married when she was 22 and he was 23. The couple, who live just outside Bristol, live in a four-bedroom, detached house and managed to pay off their mortgage two years ago when Rachel was 43. Rachel explained: “We bought our first house, a mid-terraced, two-bedroom in 2002 for about £101,000 and we got married the year after in 2003. “To buy our first home, we had a loan from my in-laws and made an agreement that they would lend us £10,000 and they would make 10 per cent of whatever profit when we sold it. “We stayed in our first home for three years and then we sold it for about £120,000 and bought a three-bed, semi-detached home for £164,000 in 2005. My in-laws got about £14,000 so when we moved into our second home, we didn’t owe them anything.” Rachel, who works freelance in public relations and whose husband is an engineer, says they lived in their second home until 2013 and had their daughter in 2009 and their son in 2012. As soon as their son started walking, they realised they needed a bigger home and moved to their current four-bedroom, detached home in April 2013, which they bought for £320,000. “We borrowed £208,000 on the mortgage and it was a 25-year term, so it was like starting again,” said Rachel. “But when we first bought a home, mortgage rates were around 5.5 per cent. However, back in 2008-09, the Bank of England base rate was really low. “So every time rates fell, we just kept our payments the same and overpaid our mortgage and kept ploughing more into our monthly payments. “At one point, our monthly payment was £360 and we were paying £1,750. We ended up paying our mortgage off 14 years early and worked out we saved between £42,000 and £45,000 in interest.” Rachel added: “When rates went down, we could have easily said we’ll just keep that extra money. We’re not skinflints, but we’re not massive spenders either. For us, the key thing was becoming debt-free on the mortgage and going on holidays. “Now we have paid off the mortgage, we can go on better holidays.” ‘I’m saving money off my mortgage just by doing my food shopping’ James Shaw, 40, and his wife Danielle moved into their three-bedroom, detached home with their two children in September 2020. The property cost £220,000 and they took on a £156,000 mortgage after selling their previous home. James, who is a paint supervisor at BAE Systems, discovered mortgage app Sprive in February this year and is using the cashback and referral rewards earned through it, as well as the autosave feature. He is already on track to save £28,000 in interest and shave six years and three months off the term of his mortgage – and more than £10,000 of that is just from the “free money” he has earned in cashback. James Shaw with his wife Danielle. The father of two is determined to pay off his mortgage early and uses the mortgage app Sprive He is also overpaying on his mortgage directly and has calculated that by just paying what he currently is, together with the savings through Sprive, he will save almost £49,000 in interest and 10 years and 11 months from his mortgage. James, 40, said: “I spend around £500 a month on food through Sprive and I am getting rewards to pay off my mortgage simply for spending money I was going to spend anyway. “I want to be able to pay off my mortgage early as it will give us that freedom and the feeling of having got rid of a financial burden. “It will take the pressure off, especially with the current climate and interest rates being quite volatile.” Jinesh Vohra, CEO of Sprive, said: “With interest rates still being relatively high, the earlier you start overpaying, the bigger the impact.”
Meet the people who repaid their mortgage years early – saving up to £45,000
Full Article
Original Source
Read the full article at Inews →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.