
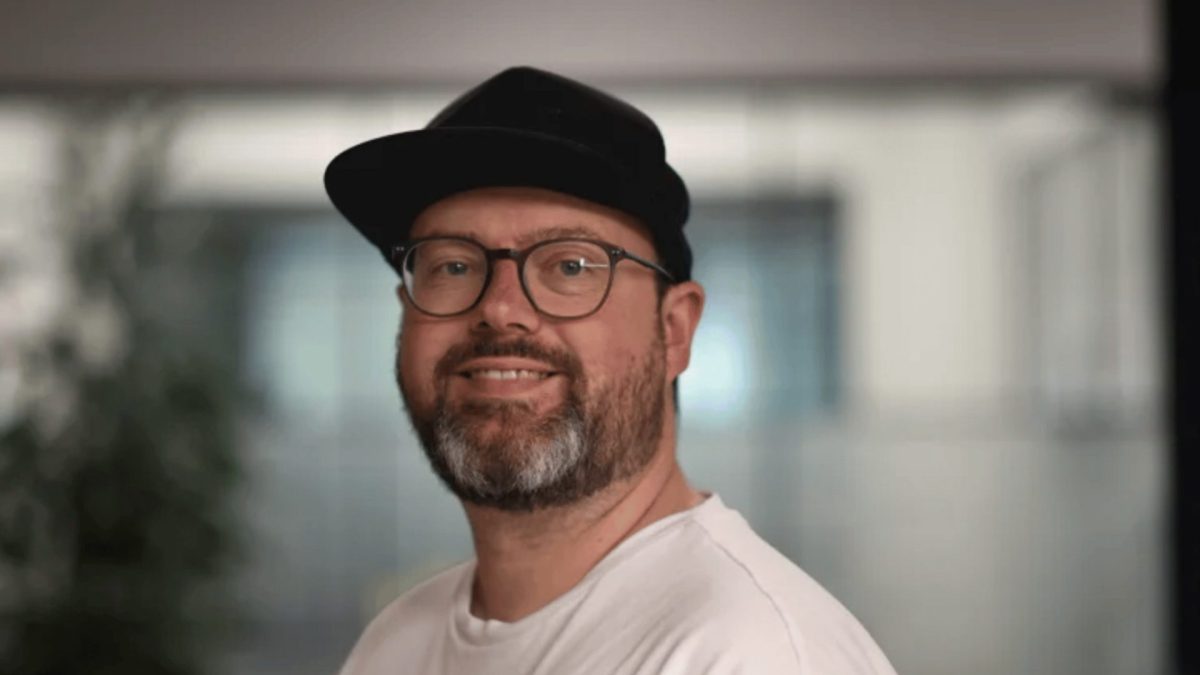
In our How I Manage My Money series we aim to find out how people in the UK are spending, saving and investing money to meet their costs and achieve their goals. This week we speak to Andy Frobisher, 40, a search engine optimisation (SEO) consultant, living in Morecambe, with his daughter, who is three. Andy is in favour of a wealth tax in the UK and thinks more utility firms should be nationalised. He had an inheritance from his father which enabled him to go freelance. Monthly budget My monthly income: The amount of money I make from my freelance SEO consultancy business varies, but is typically just over £6,000 a month. It was £7,000 a month earlier in the year. My monthly outgoings: Rent, £875; council tax, £105; groceries, £350; gas and electric, £50; water, £20; broadband, £18; mobile, £55; TV licence, £15; contents insurance for home, £7; car insurance, £119; car repayment, £291; car fuel, £120; life insurance, £22; subscriptions like Amazon Prime, Spotify and Netflix, £50; nursery costs, £250; money into savings, £100; eating out and takeaways, £50 to £100; clothes for my daughter, £50; day trips, £100. I’ve lived in Morecambe all my life and love being by the seaside. I studied film, TV and radio at the University of Staffordshire. I did multiple minimum-wage jobs for years, working in retail, administration and at a washroom servicing company, helping to retain customers. Later on, someone gave me the chance to get into marketing and I worked in agencies for years. My pay in one agency was £28,000 in 2019 but rose to £50,000 a year from 2023. By this point, I was heading up the SEO team in a marketing agency. I’ve only been earning better money in the last few years. I’d always wanted to run my own business, as my father had his own security alarm business. After having my daughter, I knew I needed to change my life. Working full-time while looking after my daughter was challenging and I wanted to be more present for her. Shorts My father died not long after my daughter was born and I was fortunate to get a £12,000 inheritance from him. His inheritance was shared between myself and four other siblings. Most of his money went on care costs as he had Alzheimer’s. The money from my father gave me a financial safety net I could rely on when I decided to go freelance. I quit the agency I worked in in February 2024 and set up my freelance business in April 2024. In the first few months, it was very difficult. In my first month as a freelancer, I made £375 but all my bills were still coming in. In the second month, I made £2,000 and it went up from there. By the third month, I was making £3,500 a month. I’m now making about £6,000 a month. I help businesses be more visible online, including in artificial intelligence online overviews. Being freelance, making sure you have enough money coming in each month isn’t easy, but my income is consistent now. I wear multiple hats and do the administration, bookkeeping, marketing and project management. I have never been a good saver. I’m autistic and can be impulsive with my spending. I like the dopamine hit I get from buying collectable Pokémon cards. But having my daughter has made me more careful with money. As a single dad, everything is expensive now. I still feel the pinch even though I am making decent money. If I have a few bad months in my business, my financial situation could change very quickly. I think a wealth tax should be introduced by the Government in the UK. The very wealthiest could shoulder the extra financial burden. The money could help fund better care for our ageing population who need to be looked after properly. I saw my dad in care and it was not good. Utility costs also need to be cheaper for people and I think more utility firms should be nationalised and put in government control. The Government has to find ways to reduce costs for people. I’m renting a two-bed flat which costs £875 a month. I need an extra set of self-employed accounts to be in a better position to get a mortgage. I’ve got about £28,000 saved up for a deposit following the sale of the house I used to share with my wife before we divorced last year. I’d like a two-bed house close to where I am now, which would probably cost about £170,000. I don’t want to be paying off a massive mortgage when I’m 70. I add £100 a month to a savings account. I have £20,000 in a cash ISA, about £500 in investments and a few thousand pounds in other savings pots. Pensions were not a priority for me until recently. I have about £22,000 in pensions. It was only when I had my daughter that I started taking pensions more seriously. I spoke to a financial adviser about it last year and consolidated all my pensions. At the end of each financial year, I now work with my accountant to figure out how much I can add to my pension. I added about £5,000 to my pension last year and want to consistently add around £7,500 a year to it until I hit 65. I wish I had been able to add more money to pensions when I was younger. Relying on the state pension alone would be very difficult. Money means more to me now as I want my daughter to be secure and I need to work towards having a good retirement. I’m happy with my income and business but would like to turn my consultancy into an agency model in the future and employ people. Want to take part in How I Manage My Money? Email money@theipaper.com
How I Manage My Money: Consultant, on £6,000 a month, with £22,000 in pension
Full Article
Original Source
Read the full article at Inews →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.