
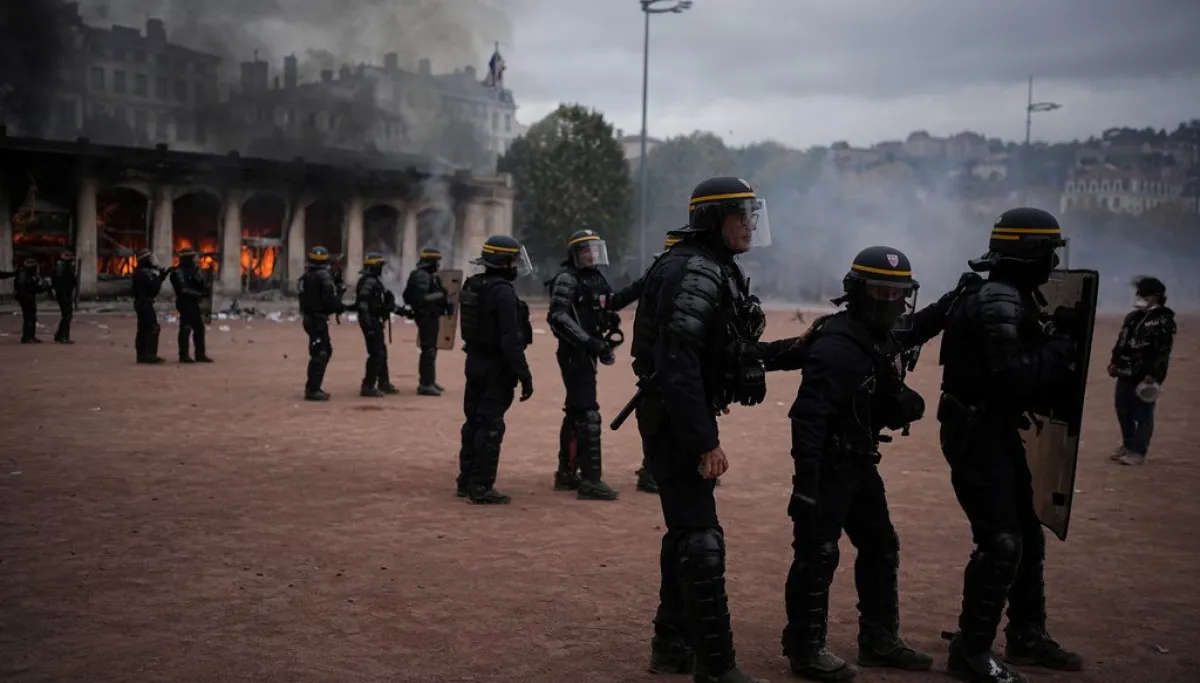
Before deriving pleasure from France’s present economic and political turmoil, President Donald Trump might want to consider that France’s current bond market crisis could have serious adverse spillover effects for the U.S. economy. This is not least because France is Europe’s second-largest economy and has a $4 trillion public debt, some eight times the size of that of Greece.It must also be of concern that, like France, the United States has unsustainable public finances and lacks the political will to address its chronic budget deficit. Those factors have already had the effect of driving up U.S. long-term Treasury bond yields to their highest level in the past 20 years.France’s present bond market crisis has been long in the making. Years of budget profligacy have led to a situation where the country’s public debt as a share of its economy has risen from 80% in 2010 to 120% today. That is not very different from the level Greece’s debt reached on the eve of its 2010 sovereign debt crisis. There is every prospect that France’s public debt will continue to mushroom, considering that, on present policies, its budget deficit is projected to increase from 5.4% of GDP today to 6.8% of GDP by 2030. It also does not help matters that France’s sclerotic economy is now being hit by an energy price shock in the wake of the Iran war, a spike in interest rates, and a flood of Chinese imports. Reflecting market concerns about France’s public finances and its seeming inability to do much about them, France’s 10-year bond yield has increased to 4.9%. That is its highest level with respect to the comparative German bond yield since 2010.Adding to France’s bond market crisis is its seeming political dysfunction. Over the past few years, President Emmanuel Macron has cycled through numerous prime ministers in his effort to cut public spending and reduce France’s gaping budget deficit. With a presidential election now scheduled for April next year and with student and labor unrest gathering pace, there is little prospect that France will be able to make any meaningful cuts in public spending over the next six months. That spending now stands at a staggering 57% of GDP, the highest level among the Group of 7 countries.Further weighing on French bond market sentiment are electoral promises being made by the two leading presidential candidates to replace Macron. Marine Le Pen, the front-runner, is promising to reduce the pension age and to cut the value-added tax on food and energy. Meanwhile, Jean-Luc Melenchon, her likely second-round rival, is proposing to burn that part of the country’s public debt held by the Banque de France.In principle, the European Central Bank has the means to bail France out by purchasing unlimited amounts of its government bonds. However, to do so, the ECB would need France to make a credible commitment to an economic adjustment program. That would seem to be a big ask in the run-up to a presidential election. The ECB would also need to get buy-in from Germany, its largest shareholder, at a time when the right-wing and anti-European Alternative for Germany party is on the march.All of this suggests that in the months immediately ahead, France’s bond market crisis is likely to deepen. That must be expected to focus the market’s attention on other countries, such as Italy, Japan, the United Kingdom, and the United States, which also have public debt sustainability problems. It might do so in much the same way that the 2010 Greek sovereign debt crisis quickly spread to the rest of the Eurozone periphery, including Italy, Ireland, Portugal, and Spain.OPINION: AMERICA IS SPENDING $3 BILLION A DAY JUST ON INTEREST. WHY IS NO ONE RUNNING ON IT?One reason this should be of particular concern to the Trump administration is that our public finance outlook looks uncomfortably similar to that of France. According to the International Monetary Fund, our budget deficit is projected to remain at over 7% of GDP over the next few years. Meanwhile, our public debt in relation to the size of the economy is projected by 2029 to exceed its level at the end of World War II.With long-term U.S. Treasury bond yields already at multi-decade highs, the last thing that we need is a further spike in interest rates triggered by a bond crisis abroad. Such an increase would mean higher mortgage rates, auto loan rates, and other key borrowing rates that would constitute a serious headwind to our economic recovery. It could also be the trigger that causes the artificial intelligence stock market bubble to burst, and it could add serious strain to a highly leveraged financial system.American Enterprise Institute senior fellow Desmond Lachman was a deputy director in the International Monetary Fund’s Policy Development and Review Department and the chief emerging-market economic strategist at Salomon Smith Barney.
France’s threat to the US’s economic recovery
Full Article
Original Source
Read the full article at Washingtonexaminer →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.